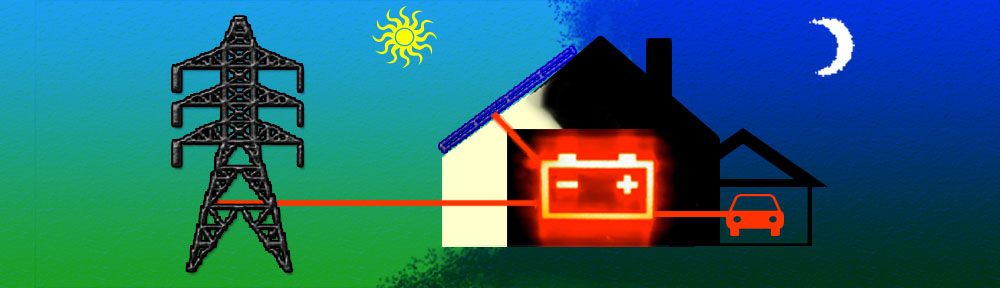
OECD Advocates Investment in Infrastructure

It’s a point we’ve been peddling for years now, but it looks like the OECD have at long last come to the conclusion that investment in infrastructure is in fact an excellent idea. By way of some proof that we haven’t been in a minority of one up to now, here’s The Economist from October 2014, underneath a picture of a parrot pushing up the daisies:

Germany’s chancellor, Angela Merkel, should allow France and Italy to slow the pace of their fiscal cuts; in return, those countries should accelerate structural reforms. Germany, which can borrow money at negative real interest rates, could spend more building infrastructure at home.

That would help, but not be enough. It is a bit like the early years of the euro debacle, before Mr Draghi’s whatever-it-takes pledge, when half-solutions only fed the crisis. Something radical is needed. The hitch is that European law bans many textbook solutions, such as ECB purchases of newly issued government bonds. The best legal option is to couple a dramatic increase in infrastructure spending with bond-buying by the ECB. Thus the European Investment Bank could launch a big (say €300 billion, or $383 billion) expansion in investments such as faster cross-border rail links or more integrated electricity grids — and raise the money by issuing bonds, which the ECB could buy in the secondary market.

Obviously here at V2G UK we were particularly keen on the bit about “more integrated electricity grids”. More recently the United Kingdom’s House of Commons Energy & Climate Change Select Committee put much the same message this way:

This promising new demand-side response technology has been disadvantaged in the auctions under the Government’s Capacity Market – meaning costs and emissions could be higher than necessary. Only a fraction of the £1 billion pounds that will be spent keeping the lights on through the Capacity Market will actually provide new capacity and just 0.4% will go on demand-side response – with most of the rest going to existing fossil fuel power stations, paying some of them to stand idle for much of the year.

Today the OECD announced its latest “Interim Economic Outlook” in a blaze of publicity under the headline “Stronger growth remains elusive: Urgent policy response is needed”:

Global GDP growth in 2016 is projected to be no higher than in 2015, itself the slowest pace in the past five years. Forecasts have again been revised down in light of disappointing recent data. Growth is slowing in many emerging economies with a very modest recovery in advanced economies and low prices depressing commodity exporters. Trade and investment remain weak. Sluggish demand is leading to low inflation and inadequate wage and employment growth.

Financial instability risks are substantial. Financial markets globally have been reassessing growth prospects, leading to falls in equity prices and higher market volatility. Some emerging markets are particularly vulnerable to sharp exchange rate movements and the effects of high domestic debt.

A stronger collective policy response is needed to strengthen demand. Monetary policy cannot work alone. Fiscal policy is now contractionary in many major economies. Structural reform momentum has slowed. All three levers of policy must be deployed more actively to create stronger and sustained growth. The recipe varies by country, especially with regard to needed structural reforms.

Diving into the depths of the OECD report itself, the bit that caught my attention runs as follows:

A stronger collective fiscal policy response is needed to support growth and provide a more favourable environment for productivity-enhancing structural policies. Governments in many countries are currently able to borrow for long periods at very low interest rates, which in effect increases fiscal space. Many countries have room for fiscal expansion to strengthen demand. This should focus on policies with strong short-run benefits and that also contribute to long-term growth.

A commitment to raising public investment collectively would boost demand while remaining on a fiscally sustainable path. Investment spending has a high-multiplier, while quality infrastructure projects would help to support future growth, making up for the shortfall in investment following the cuts imposed across advanced countries in recent years. These effects would be enhanced by, indeed need to be undertaken in conjunction with, structural reforms that would allow the private sector to benefit from the additional infrastructure; notably in the Europe Union, cross-border regulatory barriers are a significant obstacle.

Here’s a video of the proceedings in Paris earlier today:

The presentation was given by Catherine Mann, the OECD’s chief Economist, and the bit where she mentions the OECD’s concerns about the need for fiscal stimulus and investment in infrastructure is is around half an hour into the video:

Implementation of the “Juncker” investment plan has yet to deliver the targeted boost to investment. The further harmonisation in regulation needed to make the plan work also lags.

Note also Ms. Mann’s remark during the Q&A session, at around 48 minutes:

Fiscal spending on just any old thing, to the same white elephants, that is not the type of collective action that is going to generate the improvement in growth and the improvement in debt to GDP fiscal sustainability that we can see as possible. So our recipe is very much one that we started talking about more than a year ago. The recipe is we deploy the full set of tools that we have at our disposal as policymakers. Fiscal and monetary policy under the demand side, and a range of structural reforms that are unique to each country, depending on what it is they need to do.

Energy and Climate Change Committee Discusses V2G

Last year the United Kingdom’s House of Commons Energy and Climate Change Committee launched an inquiry into low carbon network infrastructure in the UK. Initially they sought written submissions of evidence, and are now televising live oral submissions to the committee. Fortunately these events are also recorded, and during the one that took place on January 12th there was much discussion of energy storage in general and electric vehicle batteries in particular. Here’s an extract:

Amongst a variety of other contributions you can hear the chair Angus MacNeil MP ask:

To what extent will electricity demand in future exhibit greater peaks and troughs due to the electrification of heat and transport? What changes will that make in demand?

The first expert witness to respond was Sara Bell, the Chief Executive of Tempus Energy:

I think that depends very much on how we manage that demand. Both the demands that you have mentioned are highly flexible, so that offers an enormous opportunity to match that demand to generation, and variable generation can be matched very successfully to that flexible demand. Every electric vehicle could be charged when we have excess renewable generation. There is a way, from an economic standpoint, of managing that sensibly.

The experts went on to discussheat pumps for bit, and then Dr Philipp Grünewald from the Environmental Change Institute at Oxford University pointed out that:

Electric vehicles could play a very interesting role in helping to balance the system, because they have inbuilt storage, but another debate is ongoing on the extent to which you want to use that type of storage for the grid. We might come back to that.

to which Dr Jill Cainey of the Electricity Storage Network added:

On electric vehicles, it is more that the charging is the critical thing that you need to control, not necessarily using the battery device for the system services. National Grid has a project in which it has looked at that — at providing frequency response.

You may correctly surmise from the name of this blog that I don’t entirely agree with Jill on that point! “Smart charging” certainly has its place, but so might “using EV batteries for system services” in a rather different market and regulatory environment to the current one. The panel discussed that issue a bit later in the proceedings. Sara Bell again:

We have not even started the process of making the demand side flexible. Tempus Energy is the only electricity supplier that unlocks flexibility in customer premises. We go to our customers and we put control and sensor technology into their premises so that we can move their demand. Every time — and I mean every time — we go into customer premises, they are using electricity at times in a very expensive way, completely unnecessarily, because no supplier has ever rewarded them for their flexibility before, so why should they bother?

We are one small new supplier. If the whole market operated like this, we would unlock a great deal of flexibility, which would reduce the total system cost.

Jill Cainey again:

There are some issues with capacity now. That is why we have the capacity market. I guess Electricity Storage Network would argue that that incentivises particular types of technology for security of supply but doesn’t necessarily support the new innovative approaches such as demand side and electricity storage because of the way that market has been designed…

There are technologies and approaches, such as demand side response and aggregation — aggregators are providing demand side response as well. We need to facilitate those approaches to move forward. That is a market approach.

That we can agree on 101%, and I also agree with Dr Gordon Edge who is Director of Policy at RenewableUK who said:

I would argue that some of the time-limiting steps are not technology but the regulatory market approaches. We need to be thinking about how we make the market so that these things, when they are economic, just happen automatically. At the moment, there are too many barriers.

and with Stephen Goldspink who is Director of Strategy and Business Development at Siemens Energy Management, who added that:

Technology and solutions are already available, as my colleagues has already said, so it is about how fast we deploy those technologies and the regulatory barriers that need to be removed to deploy them. Energy storage, demand side management, energy efficiency — all these things can support this capacity margin issue and put us on the journey to low-carbon networks much quicker.

Angus MacNeil then said:

Thank you. I understand what you are saying about regulatory barriers, but we will leave that section there.

Hence so will we, for the moment at least.

Fuelling the Debate About the UK’s Energy Future

This morning the United Kingdom’s House of Commons Energy and Climate Change Select Committee published its latest report, entitled “Fuelling the debate: Committee successes and future challenges”. The introduction to the report states that:

The Energy and Climate Change Committee plays a central role in scrutinising and improving the Government’s policy and legislation.

We look in detail at three case studies – electricity market reform, competition in the energy market and shale gas – each of which highlights the key role we have played in holding the Government to account and improving policy and legislation. Finally, we set out our future vision for the UK energy system, based on the views and evidence provided by the wide range of stakeholders that we work with. We also explore the challenges which will need to be overcome in the next Parliament if the UK is to achieve its ambitious long-term climate and energy goals.

The committee has also just released a video summary of their activities over the last 5 years. Here it is:

In the video Tim Yeo, who is chair of the committee, says amongst other things that:

The cheapest form of energy is the energy we don’t use in the first place. Yet despite the fact that energy efficiency is one of the cheapest ways to cut greenhouse gas emissions and improve energy security and end fuel poverty, they were neglected in the Government’s original proposals. So the committee recommended that demand reduction and energy efficiency be placed at the very heart of Electricity Market Reform.

Unfortunately today the Government is still putting too much emphasis on building new electrical generating capacity, instead of promoting demand-side measures that would improve security of supply and also reduce consumer bills.

Here at V2G we cannot help but agree with those sentiments. We also cannot help but agree with Catherine Mitchell, Professor of Energy Policy at Exeter University, who according to a “Tweet” by the ECC select committee itself at least, pointed out this morning that:


Professor Mitchell’s slides for her presentation this morning can be downloaded from the IGov web site.

Energy and Climate Change Committee Criticise Capacity Market

The UK’s House of Commons Energy & Climate Change Select Committee issued a report today on the implementation of Electricity Market Reform which is highly critical of the new electricity capacity market. This may strike you (as it does me!) as a severe case of shutting the stable door after the horse has bolted, but nonetheless the executive summary puts it this way:

The Government’s flagship Electricity Market Reform was designed to drive investment in our energy infrastructure and manage the transition towards generating low-carbon, secure and cost-effective electricity. After years of planning, the Government has successfully put in place the necessary framework for the first Capacity Market and Contract-for-Difference (CfD) auctions under EMR, and DECC, National Grid and the Low Carbon Contracts Company have been helpful in preparing industry in the run-up to the auctions.

However, the speed at which participants have had to assimilate the complex policies have made it a challenging environment for smaller companies, and DECC is still failing to ensure that demand-side response (DSR) providers are given a level playing field in the Capacity Market. In order to avoid paying for more expensive generation capacity that may not be needed in the future, the Government should consider means to further support DSR in the Capacity market, for instance by increasing the contract length of DSR capacity agreements.

There also remain strong concerns around National Grid’s potential conflicts of interest as EMR Delivery Body, and it is important that clear steps are taken to ensure that it does not have an unfair commercial advantage in future Capacity Market auctions.

Speaking as one of those “smaller companies” it seems from our perspective that the playing field is indeed located on a rather steep slope! Tim Yeo, chairperson of the committee, said that:

Every consumer in the country is currently subsidising spare electricity generating capacity that may only be used for a few hours each year. But smart technology has now made it possible to reduce unnecessary electricity demand at peak times, thereby reducing the number of polluting power stations that need to be switched on. This could mean we can reduce the total electricity generating capacity that has to be maintained in future, bringing down costs for consumers while enabling us to reduce consumption of fossil fuels.

Yet this promising new demand-side response technology has been disadvantaged in the auctions under the Government’s Capacity Market – meaning costs and emissions could be higher than necessary. Only a fraction of the £1 billion pounds that will be spent keeping the lights on through the Capacity Market will actually provide new capacity and just 0.4% will go on demand-side response – with most of the rest going to existing fossil fuel power stations, paying some of them to stand idle for much of the year. Nearly a fifth of the capacity contracts already awarded are going to highly polluting coal power stations.

Which sums things up quite nicely for us. We would go even further than Tim Yeo. Not only should Demand Side Response be getting a better deal, so should distributed energy storage in general and V2x in particular. Tim does however also point out that:

The results of the first CfD auction for long term low-carbon contracts show that small companies or community energy projects are in danger of being shut out. The fact that the final strike prices were cheaper than the administrative price is a very positive result, but it casts further doubts over the value-for-money of the early contracts for renewables under the Levy Control Framework.

The committee’s concluding bullet points read as follows:

DECC’s upcoming review on EMR should focus hard on the issues voiced by stakeholders and raised in the Committee’s report. In particular, it should focus on:

  • The role of highly polluting coal and diesel fired power generation in the capacity market
  • How to facilitate cheaper and cleaner demand-side solutions to keep the lights on
  • How potential conflicts of interest with National Grid will be avoided or addressed
  • How engagement with small players can be improved

to which we would add one of our own:

How to design UK energy markets such that distributed storage and generation operate on a level playing field?