Last week there was a significant “Energy Technology” announcement in Manchester. This article was supposed to be written/published last weekend, but Storm Darragh and our subsequent 20 hour power cut proved more than capable of disrupting the carefully laid plans of both mice and men!
Hastily returning to a rather damp Manchester on December 5th, here is a recording of the meat of the initial presentation by Devrim Celal, Chief Marketing and Flexibility Officer of KrakenFlex Limited, speaking at the launch of the “Mercury Consortium” at the “UK’s first energy tech superhub”:
Devrim’s presentation was followed by a panel session with representatives of four “manufacturers”, which we will cover at a future date. After a “networking break” there was another panel session with speakers from four “utilities”, introduced by Arshad Mansoor who is President and CEO of the Electric Power Research Institute. Here’s what Arshad had to say:
How do you catch a cloud and pin it down? How do you find a word that means Flexibility?
We’ll get back to answering that question in due course. First some exciting news.
On November 22nd I attended the kick off meeting of a new International Electrotechnical Commission “smart grid” committee. This one is catchily entitled the “System Committee Smart Energy ad hoc Group 11 on Energy flexibility and residential DSR: common ground”, or “SyC SE ahG 11” for short.
If you follow the link just above you will discover that ahG 11’s mission is:
To consider the implementation of international residential flexibility system standards, their compatibility with national requirements, and propose best practice:
* To ensure the compatibility of end-to-end system solutions at international level,
* To identify emerging challenges related to the uptake of residential DSR,
* To consider terminology alignment, and
* To develop an accelerated report containing requirements for residential flexibility. This would give recommendations for alignment of existing national publications and flexibility projects under development with international standards. It would also identify, if relevant, the need for further standardization
Amongst other questions discussed at the kick off meeting was “How do you define the term ‘flexibility'”. Your mileage may vary of course, but since I spent 5 years of my life meeting 2 or 3 times per week on the committee developing the IEC 63110-1 document I will quote from the Committee Draft for Vote (CDV for short) of that international standard:
General concept of elasticity of resource use, (demand, storage, generation) modification of consumption and/or generation of energy/power, on an individual or aggregated level, in 371 reaction to an external signal (price signal or request) in order to provide a service within the energy system
Elasticity of resource use (demand, storage, generation), modification of consumption and/or generation of energy/power, on an individual or aggregated level, in reaction to an external signal (price signal or request) in order to provide a service within the energy system.
If you have strong objections to that definition please do not hesitate to join ahG 11, or failing that to send your preferred term of words to me so that I can bring it to the committee’s attention.
My other main action item before the next meeting in the New Year is to generate a list of existing standards, regulations etc. relevant to my particular area of expertise, which is bi-directional power transfer during electric vehicle (dis)charging (BPT for short). More commonly referred to as V2x. Since ahG 11’s term of reference includes the word “residential” this suggests an emphasis on vehicle-to-home technology (V2H for short) . However, homes are of course connected to the local electricity distribution grid, and are not forbidden from feeding electrical energy back into the grid as long as all the associated rules and regulations are adhered to.
Please let me or any other member of the committee know of any “standards” within your own area of expertise that may be relevant to “residential demand side response” (using the UK’s non standard nomenclature!), whether they be international, national, “industry de facto” or even the learnings from relevant “pilot projects”.
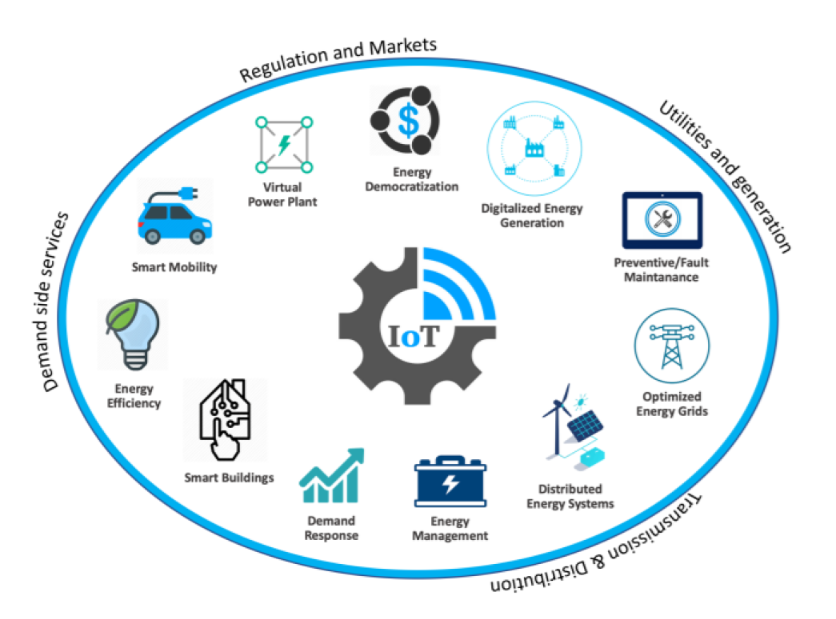
Please feel free to suggest candidates for “standards” for communicating across any of the arrowed lines in the diagram, and alternative diagrams for that matter!
In response to the massive growth of renewable energy in the Netherlands, Renault Group, We Drive Solar, MyWheels and the City of Utrecht have joined forces to launch Europe’s first large-scale car-sharing service utilizing Vehicle-to-Grid (V2G) technology.
Renault Group will supply 500 Renault 5 E-Tech electric equipped with Mobilize’s V2G technology.
We Drive Solar will provide and operate bidirectional charging stations.
MyWheels, the leading car-sharing platform in the Netherlands, will operate the fleet.
Utrecht is taking a bold step towards more sustainable mobility with this groundbreaking collaboration. This initiative aims to facilitate the large-scale availability of electric shared mobility while offering an innovative way to balance the city’s electric grid through bi-directional charging technology. The Netherlands has become a world leader in the roll-out of solar and wind energy, causing challenges on the electricity grid. Utrecht is one of the most advanced European cities in using renewable energy, with already 35% of all rooftops covered with solar panels.
Eleanor Warburton, Interim Director of Energy Systems Management and Security at Ofgem, has written an open letter to:
The CEOs of the Energy Networks Assocation, the Distribution Network Operators and National Grid ESO
Here are the first few paragraphs:
I am writing to you to emphasise the importance of the Open Networks Project and the flexibility-enabling activities it is driving forward, which remain a priority for Ofgem.
Flexibility at scale is essential for achieving net zero. We recognise there has been progress made in recent years in developing flexibility markets, but we are clear that further significant changes are needed to unlock the full value of flexibility.
In recent publications we proposed reforms to help unlock this value. We set out the need for fair and transparent rules and processes for procuring flexibility services, which are standardised to minimise friction. Flexibility service providers must be able to stack revenue and participate easily in open, transparent and coordinated markets.
There is strong support for the case for change and for our proposed direction of travel, however respondents raised concerns about a risk of hiatus in the growth of local flexibility markets.
We wish to emphasise that we see no reason for there to be any deceleration in progress and we strongly expect the Energy Networks Association (ENA) and Distribution Network Operators (DNOs) to continue to progress key flexibility enabling activities through the Open Networks Project. We are confident from our recent engagements that you, the ENA and DNOs, share this view too.
The importance of growing local flexibility markets and standardising rules and processes for procuring flexibility services is reflected in RIIO-ED2 arrangements and the Distribution System Operation (DSO) incentive. Any loss of momentum could impact DSO incentive performance, through both the stakeholder survey and the performance panel assessment.
The Open Networks Project has been pivotal to the growth of local flexibility markets in the UK and building on that to drive further, faster success is very much a priority for Ofgem. We look forward to seeing the progress it makes over the coming year.
We are not seeing the scale of distributed flexibility that we need due to market access and coordination issues. This is especially true for Consumer Energy Resources (CER) like electric vehicles and heat pumps. We need a flex-centric system which facilitates distributed flexibility, but it is not clear that this will emerge organically.
I remotely attended several sessions at the recently completed COP26 conference in Glasgow, but what with one thing and another I missed out on attending this one as it happened:
As you can already see it was organised by Scottish and Southern Electricity Networks (SSEN for short) and was hosted by Laura Sandys. Note in particular the part at 6:30 where Professor Malcolm McCulloch of Oxford University says that:
So the challenge is to say “How do we allow that potential problem and risk, how do we turn that around to be something that’s really a friend and an aid to the system?”
And the one thing that worries me right at the moment is that we’re seeing a huge uptake in electric vehicles over the last while, I mean it’s kind of fascinating that at the beginning of this year the most popular vehicle being sold was the Ford Focus, last three months it’s been the Tesla Model 3! That kinds of tells you what the change in our dynamics is looking at.
At the moment we’re missing a trick because most of the vehicles being sold except for a few Nissan’s and a few others don’t have vehicle-to-grid. In other words the power flows in only one direction, so all that huge amount of storage capacity that’s available on the grid, we’re talking about by the time we get to 2030 there’s enough energy in the batteries of our electric vehicles to power the UK for two days. That’s a tremendous amount of energy that’s sitting there, but if we don’t install V2G soon, really soon, that boat is going to pass and we’re going to have real trouble in trying to, or much more costly ways of doing that.
Needless to say we broadly agree with Malcolm’s analysis, and the conversation in Glasgow continued. Please watch the whole 30+ minutes, but now there is further news. The Local Energy Oxfordshire project (LEO for short) has just released a white paper authored by Origami Energy and the Low Carbon Hub catchily entitled “Vision on the inclusion of small (under 7kW) flexibility from the grid edge and its role in Future Energy System“. Please also read it from cover to cover, and note that it briefly (and belatedly!) mentions that:
In 2021, British Standards Institute as part of [its] Smart Energy Appliance programme published two standards designed to support [a] testing and certification programme to motivate greater potential for demand response from [the] residential sector.
Note also LEO’s recommendations:
Grid-edge flexibility has great potential to be the enabler of Net Zero as outlined by the “Leading the Way” FES scenario. However, t he two biggest challenges facing the inclusion of small flexibility from the grid edge into delivering Net Zero are societal participation and commercial environment. A common pillar to both challenges is the value of flexibility which only partially reflects the benefits delivered through the flexibility markets. Today, each flexibility market is monopsonistic (market dominated by one buyer), segregated and short-term (there is a lack of long term stability in the regulatory landscape). There is a need to standardise products and services across all flexibility markets to encourage greater transparency and involvement of flexibility as these flexibility markets grow.
To support the inclusion of grid-edge flexibility, the proposed recommendations include:
• To tailor the legislation and regulation to support the development of local communities who act collectively to manage their LCTs and interact with the flexibility markets and other users of the system at a single node (e.g. enabled by an iDNO) or multiple nodes.
• Create a new energy and carbon marketplace to encourage wider deployment of Smart Local Energy Systems where local generation and demand flexibility is recognised as being critical for a healthy and affluent society. The Flexible Services players are seen to add significant benefit to the local society and also provide support to the National scale economy.
• Align the energy policy, welfare policy and housing policy to deliver long-term strategy for Net Zero and beyond ensuring balanced distribution of costs and benefits associated with grid-edge flexibility and cost of energy.